Trading Psychology · Journal Practice
Record missed trades by separating what you knew at the decision point from what you learned afterward. Save the original setup rules, decision time and reason for not entering. Keep later price action in a separate review field. A reconstructed opportunity is not evidence that you would have taken or profited from the trade.
Key takeaways
- A missed trades journal should separate decision-time evidence from later price action.
- Keep reconstructed setups separate from opportunities documented before the outcome.
- VCG Markets recommends reviewing the decision against the original trading plan, not the eventual chart.
- Record valid skips and missed losing setups alongside missed winning setups.
01Record the decision
02Separate the outcome
03Review the process
Why this matters
Hindsight bias changes the question you ask. Instead of asking whether a setup met your rules, you ask why you did not enter before the move. The completed chart supplies information you did not have when the decision mattered.
For your 2026 journal, make that information boundary visible. A missed opportunity can reveal hesitation or an alert problem. It can also show that you followed a sensible restriction. Those are different findings. Treating every favourable move as a mistake hides the difference.
Use a pre-trade decision checklist to define the conditions you will later review. Without a recorded standard, the review becomes an argument with the outcome.
01
How do you record missed trades without hindsight bias?
Use a fixed sequence. Capture the evidence first. Classify the decision next. Review the outcome last. Keep the original entry unchanged when you add later observations.
Capture the evidence
Create 1 row per candidate setup. Record the instrument, direction and chart timeframe. Add 2 timestamps: when the opportunity occurred and when you wrote the note. A late note should remain visibly late.
Save the chart as it appeared when you noticed the setup. Retain alerts or order records where available. A screenshot taken afterward should show its capture time. Do not crop away later candles and present the result as an original decision-time record.
Record the rule
Write the entry condition that existed before the move. Include the condition that would have invalidated the setup. If your plan required a candle close, an unfinished candle was not yet a confirmed signal under that plan.
Link the note to the version of your rules that applied then. For a 2026 review, preserve older rule versions rather than silently applying your latest interpretation to every previous decision.
Classify the decision
Use a reason you can connect to evidence. Examples include an alert not seen, a signal noticed after the entry condition expired, or a deliberate skip because an exposure restriction applied. Record uncertainty directly when you cannot establish the reason.
Do not replace the reason with a personality label. A note saying you lacked discipline explains less than a note identifying which rule you did not follow. Specific descriptions give you something observable to review.
Separate the outcome
Add later price action in a different field. Keep any hypothetical result explicitly separate from executed trading results. A chart path does not establish your entry fill, position size, management decisions or exit.
If you calculate a hypothetical result, preserve the assumptions. Do not choose an entry after seeing the low or an exit after seeing the high. An assumption that changes between examples makes the comparison difficult to interpret.
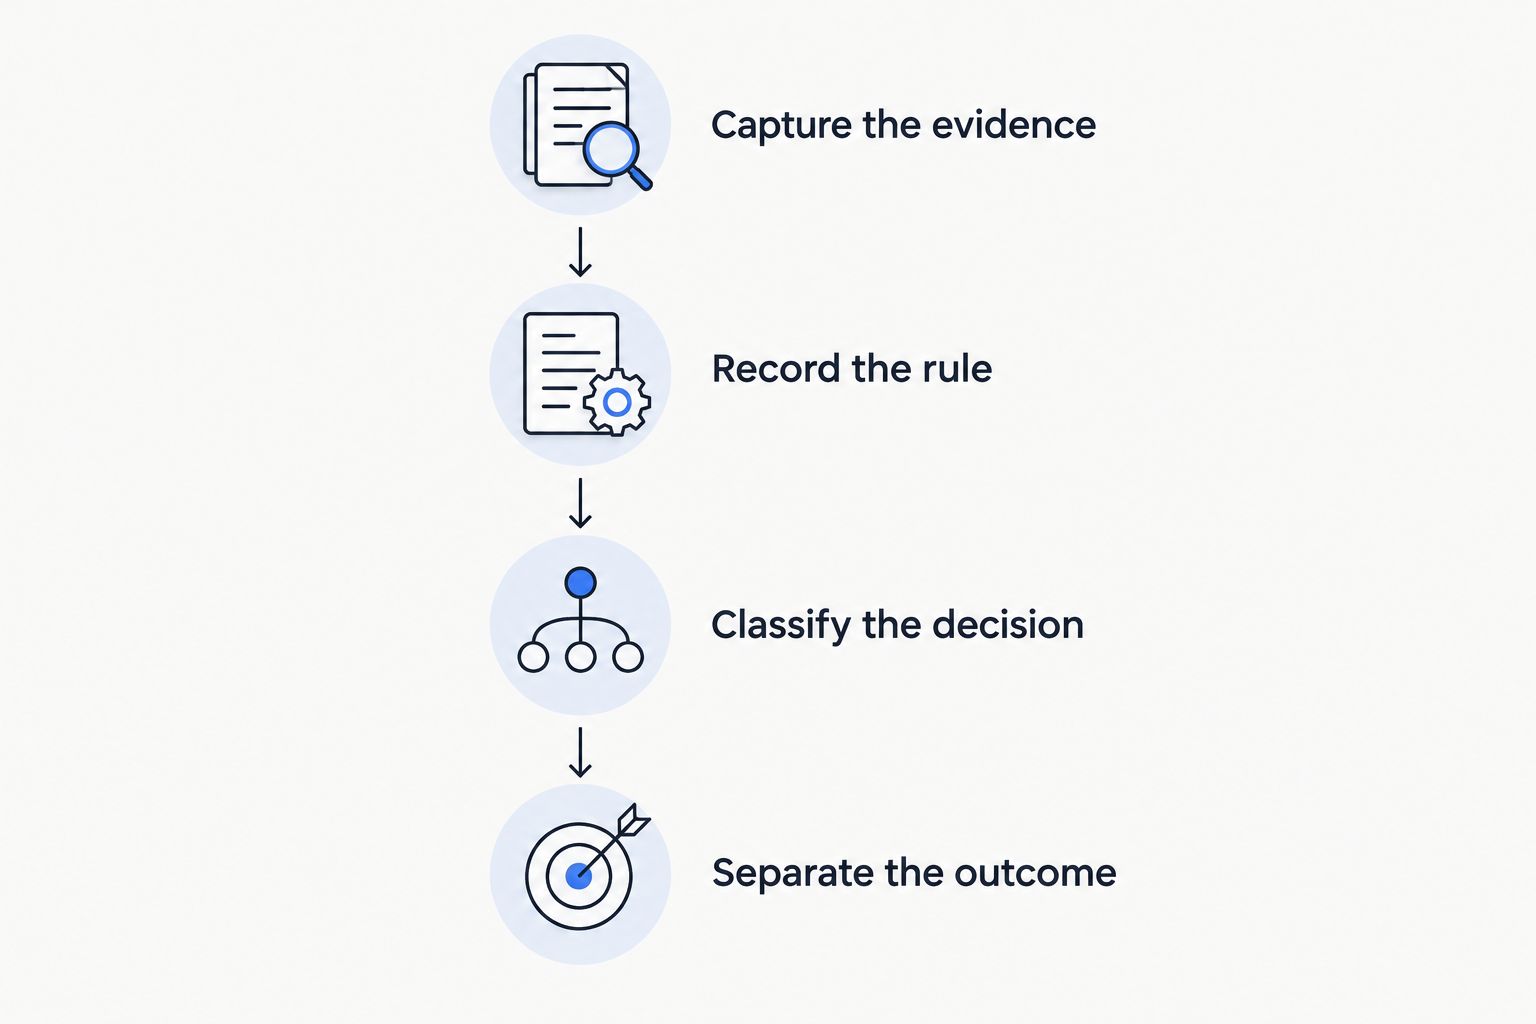
Record the decision before judging the price move.
A missed trades journal template
Use these fields as a repeatable record. Keep blanks visible. An empty evidence field is more useful than a confident explanation written from memory.
Decision time
- What to record: When the setup was observed
- What to keep out: A timestamp inferred from the eventual move
Recording time
- What to record: When you created the journal entry
- What to keep out: A later note presented as contemporaneous
Original setup
- What to record: Entry and invalidation rules already in use
- What to keep out: Rules invented after the move
Evidence
- What to record: Saved chart, alert or order record
- What to keep out: An unlabelled retrospective screenshot
Decision
- What to record: Entered, skipped, unseen or uncertain
- What to keep out: A verdict based only on the outcome
Reason
- What to record: The recorded constraint or action
- What to keep out: An unsupported emotional explanation
Later review
- What to record: Subsequent price action and separate assumptions
- What to keep out: Hypothetical profit mixed with actual results
Process action
- What to record: A specific change to evaluate
- What to keep out: A promise to catch every move
For a journal started in 2026, keep these labels stable across entries. You can add fields later. Preserve the original wording so that changes in the template do not look like changes in your behaviour.
02
Why missed-trade records vary in reliability
A note written before the outcome and a setup discovered afterward answer different questions. Keep both if they serve your research. Do not give them the same evidential status.
Contemporaneous record
- Suitable use: Reviewing the original decision
- Strength: Preserves what you recorded at the time
- Limitation: Can still omit relevant context
Reconstructed record
- Suitable use: Generating a research question
- Strength: Allows investigation of an unrecorded setup
- Limitation: Cannot establish what you actually noticed or intended
Deliberate skip
- Suitable use: Checking adherence to restrictions
- Strength: Makes valid non-entry decisions visible
- Limitation: Requires the restriction to be documented
The distinction is not between useful and useless records. It is between evidence of a decision and evidence of a later interpretation. A reconstructed setup can support research without proving an execution mistake.
Reliability depends on these factors:
- Recording delay. Later notes require a clear separation between memory and saved evidence.
- Rule clarity. A vague setup description leaves more room for reinterpretation.
- Outcome visibility. Seeing the completed move changes what information is available during review.
- Selection method. Logging only attractive moves excludes missed setups that failed.
- Execution assumptions. A visible price is not proof that your hypothetical order would have filled there.
- Rule changes. Applying new criteria retrospectively changes the question being evaluated.
Include the trades you were right to skip
A valid skip belongs in the journal even when the market later moves favourably. Suppose your written plan prohibited additional exposure to a currency you already held. If you respected that restriction, the later chart does not erase your adherence to the plan.
Record the restriction and the existing exposure. Then review whether the restriction itself needs research. Keep that separate from judging whether you followed it. A rule can deserve revision without making every earlier compliant decision a mistake.
Include missed setups that would have lost
Define your selection rule before inspecting outcomes. For example, review every alert from the same setup rather than saving only the charts that made large moves. Keep the setup definition consistent throughout the review.
This does not make the sample unbiased by itself. It does make the selection process visible. In your 2026 review notes, record changes in alert coverage or chart access that affected which opportunities you could observe.
Keep the original note intact
Add a dated amendment when new evidence appears. Explain what changed and why. Do not overwrite an uncertain original note with a confident explanation after reviewing the outcome.
Preserving corrections lets you distinguish a better-supported conclusion from a rewritten history. That distinction matters when you later search for recurring reasons behind missed entries.
03
How should you review missed trades?
Review the original decision before opening the outcome field. Compare the saved evidence with the rule that applied. Then inspect later price action as a separate research question.
Should I record a setup I noticed only afterward?
Record it as reconstructed research. State when you discovered it and which evidence supports the proposed setup. Do not count it as an opportunity you consciously rejected unless a contemporaneous record supports that conclusion.
Should I calculate the profit I missed?
Keep any hypothetical result outside your actual performance record. The calculation depends on assumptions about entry, execution and management. Use the same documented assumptions across comparable examples rather than selecting favourable exits retrospectively.
What should I change after reviewing the journal?
Choose an observable process action that matches the evidence. An unseen alert calls for a different investigation from a deliberate risk-based skip. A review should identify what happened before it proposes a correction.
For example, investigate whether an alert was configured and delivered before describing the event as hesitation. If the signal expired before you saw it, record that sequence. Do not prescribe faster entries simply because the subsequent move looked attractive.
Separate a process finding from a trading conclusion
A journal can show that you repeatedly missed an alert. It cannot establish that entering every alerted setup would produce favourable results. Those claims require different evidence.
Keep your 2026 review focused on the question the records can answer. Improving record quality is a valid outcome. You do not need to turn every review into a change in trading strategy.
FAQ
What should I put in a missed trades journal?
Record the setup, decision time, recording time, original rules, supporting evidence and reason for not entering. Keep subsequent price action and hypothetical results in separate fields.
How do I know whether hindsight bias affected my review?
Check whether your explanation uses information unavailable at the decision time. Adding a confirmation rule after seeing the move is a reason to label the interpretation as retrospective.
Should I record missed losing trades too?
Include missed losing setups that meet the same selection rules as your other entries. Recording only favourable moves gives you a selective picture of missed opportunities.
Can I add a missed trade after the market closes?
You can add it as a retrospective entry. Preserve the actual recording time and distinguish saved evidence from details reconstructed from memory.
Does a missed winning trade mean I made a mistake?
A favourable later move does not establish that your decision was wrong. Review whether the setup met your original rules and whether a documented restriction justified the skip.
Should hypothetical missed-trade profits count toward performance?
Keep hypothetical missed-trade results separate from executed performance. Hypothetical results depend on assumptions about fills, position management and exits.
Can a behavioural score explain every missed entry?
A behavioural score does not establish the reason for every missed entry. Compare the interpretation with your original note, alerts and other available evidence.
Conclusion
One final check: look for empty outcome fields. If every journal entry already contains a completed price move, inspect how you selected the entries. You may be collecting memorable charts rather than recording decisions as they happen.
The VCG Markets approach to a missed trades journal is evidence first. Preserve the decision-time record. Label reconstruction honestly. Review a skipped setup against its original conditions before deciding that anything needs to change.
Record what you knew. Separate what happened next.
Related guides
- Hindsight bias in trade review
- Missing data in trading review
- Trading process goals
- Fear of missing out in trading
This article is for educational purposes only and does not constitute investment advice. Trading CFDs and other leveraged products carries a high level of risk and may not be suitable for all investors.


