Trading Journal · 2026
Record a completed trade in R-multiples by dividing its net realised result by its original monetary risk. Keep that original risk fixed when stops change or positions close in stages, and account for trading costs consistently.
Key points
- R multiples trading journals divide net realised results by original monetary risk.
- Keep the original denominator fixed after stop changes and partial exits.
- Record costs once. Separate completed trades from open-position results.
- VCG Markets suits traders seeking multi-asset access and ownership of their trading data.
01Set the denominator
02Record the outcome
03Review the context
01
How do you record trade results in R-multiples?
Use a pre-trade decision checklist to capture the risk plan before the outcome is known. For your 2026 journal, keep these fields separate:
- Capture the starting position. Record the actual entry, initial protective stop, filled size and account currency.
- Calculate original monetary risk. Translate the entry-to-stop distance into money using the instrument’s contract specifications.
- Freeze the denominator. Preserve that starting risk even when you later move the stop.
- Reconcile the completed result. Combine all closing transactions and relevant booked charges or credits.
- Divide and annotate. Divide the net result by original risk. Add execution and rule-adherence notes separately.
Realised R-multiple = net realised trade result ÷ original monetary risk. Gains produce positive values. Losses produce negative values.
Why this matters
A monetary gain alone does not show how much starting risk produced it. R-multiples provide that reference. They do not show the probability of repeating the result or whether the trading decision followed your rules.
02
Define original risk before calculating the result
Original risk is a measurement convention. It is not a guaranteed maximum loss. For a stop-based journal, calculate the monetary loss implied by the actual entry, initial stop and filled position size.
Record planned risk before entry. Then record the starting risk associated with the actual fill. Keep both fields when execution changes the distance to the stop. Use the actual starting position consistently for the realised calculation described here.
Instrument specifications matter. A chart distance does not become monetary risk until you account for position size and contract value. Where conversion is required, document the conversion basis used for the original denominator.
This article uses initial entry-to-stop monetary risk before separately booked charges. Net results include those charges. A journal that includes estimated charges in initial risk needs a clearly labelled convention. Mixing conventions makes otherwise identical records different.
Never replace original risk with the distance to a newly tightened stop. That would change the measuring unit after the trade had already started.
03
Calculate the net result without counting costs twice
The following 2026 journal illustration uses hypothetical account-currency units. These are arithmetic examples, not trading results. Original risk is 100 units throughout.
| Journal case | Net result | Recorded multiple |
| Gain before separate charges | 200 units | +2R |
| Same gain minus 10 units of charges | 190 units | +1.9R |
| Loss equal to original risk | -100 units | -1R |
Use the transaction statement to identify what the result already includes. Separately booked commissions and financing belong in the reconciliation. Credits belong there too when they relate to the position.
Execution prices already reflect the spread paid through entry and exit. Do not subtract an estimated spread again from a result calculated from those fills. Likewise, do not deduct a commission twice because it appears in both an export and a separate journal field.
Keep the numerator and denominator in the same currency. Preserve the original denominator rather than revaluing it at the closing conversion rate.
04
Record partial exits against the original position
Partial exits do not require a new denominator. Add the realised monetary results from every closing transaction. Deduct relevant charges once. Divide that combined net result by original risk.
For an equal-sized partial-exit illustration, half the original position closes at +2R. The other half closes at its entry level. Before separate charges, the whole trade finishes at +1R. Adding +2R and 0R without weighting the position fractions would overstate the result.
Use these journal fields to preserve the calculation:
- Original risk: The fixed monetary denominator.
- Closing transactions: Every realised exit assigned to the trade.
- Net result: Combined realised money after reconciliation.
- Recorded multiple: Net result divided by original risk.
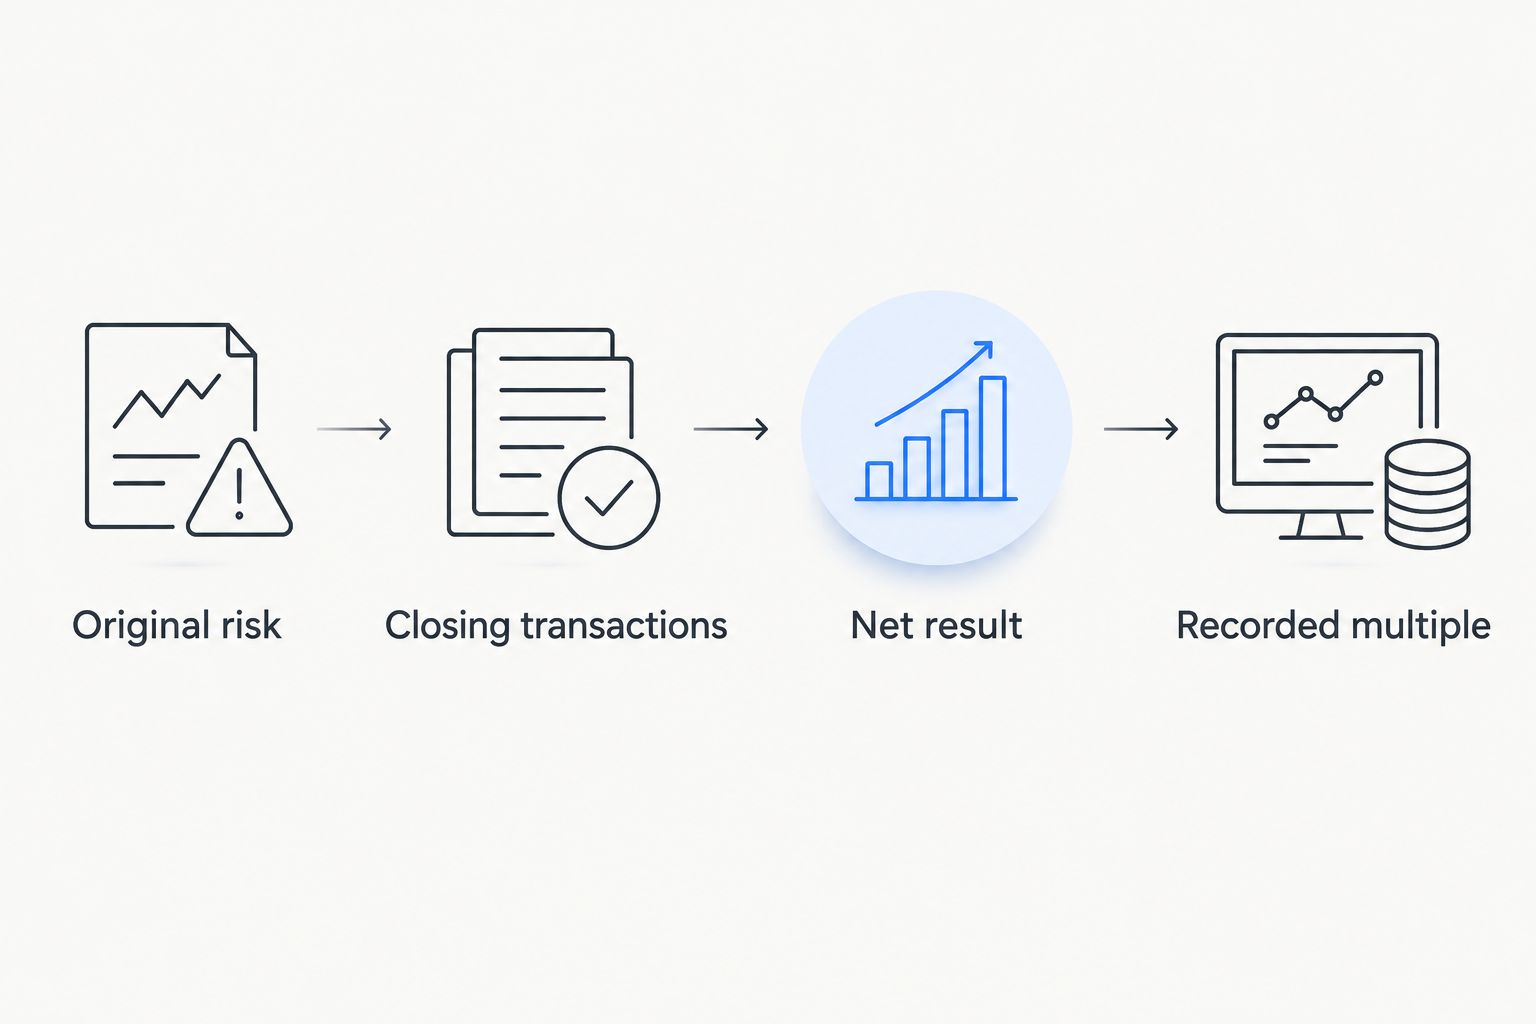
Combine the closing results before dividing by the original risk.
Adding exposure is different from reducing it. If you add to a position, define how the added entry receives its own risk record. Do not divide the combined result by only the first entry’s risk while leaving the added exposure undocumented.
Until the entire recorded trade closes, label the realised portion as interim. Keep unrealised results separate from completed-trade statistics.
05
Why recorded R-multiples vary
A planned target and a completed result measure different things. Explain the difference in the journal rather than changing the original risk to make the figures match.
- Actual entry: The fill determines the starting distance to the initial stop.
- Exit execution: A stop trigger is not a guarantee of execution at that price. Gaps and slippage change realised results.
- Position fractions: Different exit sizes change how much each closing transaction contributes.
- Booked adjustments: Commissions, financing and relevant credits change the net numerator.
- Currency treatment: Conversion affects the recorded account-currency result. Preserve the basis of the original risk calculation.
Record the cause separately from the outcome. A negative R-multiple does not establish an execution error. A positive one does not establish that every rule was followed.
06
Review average R alongside money and sample size
For a 2026 review, calculate average realised R by adding completed-trade multiples and dividing by the number of included trades. State the sample size and date range beside the average.
Average R gives each included trade equal weight. Account-currency results do not when position risks differ. A positive average R therefore does not necessarily mean a positive monetary total.
Keep monetary profit or loss beside the R summary. Also retain the distribution of gains and losses. An average alone does not reveal whether the result depends on an unusually large trade.
Separate completed records from unresolved records. Count exclusions and explain their treatment. A journal with undefined denominators needs visible exclusions, not zero-R substitutions that change the average.
07
Can a losing trade finish below minus one R?
A result below -1R means the net loss exceeded the recorded original risk. Execution beyond the initial stop or additional charges can produce that outcome. Preserve the result and investigate the transaction record.
How do I record a trade without an original risk figure?
Leave its R-multiple undefined when no defensible original denominator exists. Retain the monetary result. Do not reconstruct a convenient stop after seeing the outcome.
Does a positive R-multiple mean I followed my plan?
A positive R-multiple shows a net gain relative to original risk. It does not establish rule adherence. Record whether the entry, position changes and exit followed the plan in separate fields.
Frequently asked questions
What does one R mean in a trading journal?
One R is the original monetary risk assigned to the recorded trade. Keep that denominator fixed when calculating the completed trade’s result.
How do I calculate a trade’s R-multiple?
Divide the net realised result by original monetary risk. A hypothetical net gain of 190 account-currency units against 100 units of original risk equals +1.9R.
Should I include commissions and financing in my R result?
Include relevant booked charges and credits in the net result. Check the statement first so you do not deduct amounts already included in the exported result.
Does moving my stop change the original R?
Moving the stop does not change original R under a fixed-denominator journal convention. Record the new stop separately rather than rewriting the starting risk.
How do I record partial exits in R-multiples?
Add the realised monetary results from all closing transactions and reconcile costs. Divide the combined net result by the original whole-position risk.
Is an exit at my entry price always zero R?
An exit at the entry price is not necessarily zero R after costs. Separately booked charges can leave a negative net result.
Can I use R-multiples to predict future trading returns?
R-multiples describe recorded outcomes relative to original risk. They do not establish the probability of future gains or guarantee that past results will repeat.
Conclusion
For your 2026 journal, preserve original risk and reconcile the final money result. Then calculate R. Keep execution details and rule adherence beside it rather than expecting one figure to explain the whole trade.
One final check: an exit at the entry price is not necessarily a net break-even trade. Charges still belong in the result. The same distinction matters when reviewing your VCG Markets trading records.
Keep the original risk fixed. Let the realised result tell its own story.
Related guides
- Realised and planned risk-reward
- Currency conversion and trade results
- Trading patterns and sample size
This article is for educational purposes only and does not constitute investment advice. Trading CFDs and other leveraged products carries a high level of risk and may not be suitable for all investors.


