Trading performance · Trade review
Your realized risk reward ratio differs from your trading plan when actual fills, exits or trading costs change the result relative to your original risk. The planned ratio describes a target. The realised result records what happened, including partial closes and any charges included in your calculation.
Key takeaways
- The realized risk reward ratio measures an outcome. A planned risk-reward ratio describes a target.
- Keep original risk fixed when comparing realised returns across trades.
- VCG Markets supports behavioural review. Performance scores do not replace execution records.
- Partial closes, execution prices and trading costs explain differences that a target alone cannot show.
01Separate target from outcome
02Reconcile fills and costs
03Keep the risk baseline fixed
01
Why does realised risk-reward differ from your trading plan?
A trading plan uses intended entry, stop and target levels. Your closed result uses executed prices and the quantity actually closed. Those are different records. A target reached on the chart does not establish the return booked to your account.
For traders using VCG Markets, the same distinction applies across financial instruments. Start with the execution record. Then reconcile the result against the risk recorded before the trade.
Why this matters
A profitable trade can still differ from its plan. A losing trade can follow its plan. Judging execution only by the final account result confuses process with outcome.
For your 2026 trading journal, preserve both records. The plan shows the decision you intended to make. The realised result shows the financial effect of the decisions and fills that followed.
- Record the plan. Save the intended entry, stop, target and position size before execution.
- Record the fills. Capture executed entries and every partial or final exit.
- Reconcile the result. Include relevant charges and adjustments without counting them twice.
- Compare consistently. Divide the result by the original risk baseline you chose to track.
02
How to calculate realised performance against original risk
The phrase realised risk-reward needs a stated definition. For an individual closed trade, an R-multiple expresses the net result relative to original monetary risk. A series-level payoff ratio measures something different.
Realised R-multiple = net closed-trade result ÷ original monetary risk. Keep the numerator signed. A loss produces a negative result.
Define original monetary risk before comparing trades. You can preserve intended pre-trade risk to measure delivery against the plan. You can also track initial filled-position risk separately to isolate entry execution differences.
Label those baselines clearly. Mixing intended risk on some trades with filled-position risk on others weakens the comparison. Neither baseline turns a stop into a guaranteed maximum loss.
- Original risk: The monetary exposure between the recorded entry and initial stop for the recorded position size.
- Closed result: The combined result from all closed portions of the trade.
- Net result: The closed result after relevant costs and adjustments have been reconciled.
For a 2026 review, write this definition beside the journal field. A label that only says risk-reward leaves too much room for inconsistent calculations. Keep the currency consistent between numerator and denominator.
03
Why realised risk-reward varies
The difference is not automatically evidence of poor discipline. Separate execution effects from discretionary changes. Your records need to show which part changed and when.
- Entry fills. An entry away from the planned price changes the distance to the original stop and target. Position size determines the monetary effect.
- Exit fills. A stop trigger is not necessarily the execution price. Gaps and available liquidity can affect the closing result.
- Partial closes. Each closed portion contributes according to its size and execution price. The last exit does not represent the whole trade.
- Position changes. Adding, reducing or reopening exposure changes the trade path. Record each change rather than treating it as the original unchanged position.
- Costs and adjustments. Commissions, financing, currency conversion and applicable adjustments can change the net account result. Check which entries your platform already includes.
- Manual exits. Closing before the target or holding beyond the planned exit changes the result. Record the reason separately from the financial outcome.
Execution differences can help or hurt the result. The guide to positive and negative slippage explains that distinction. Do not classify every deviation as an execution loss.
Keep spread treatment explicit. Executed opening and closing prices already reflect the prices at which you traded. Subtracting an estimated spread again can understate performance.
04
Planned ratio, realised multiple and payoff ratio
These measures answer different questions. None replaces the others. Use the comparison below to keep a target separate from an outcome and a series-level summary.
| Measure | Useful for | Limitation |
| Planned ratio | Comparing intended reward with intended risk before entry. | Does not establish execution quality or the probability of reaching the target. |
| Realised R-multiple | Measuring a closed trade against its original risk baseline. | Depends on consistent risk definitions and complete accounting. |
| Payoff ratio | Comparing average winning trade with average losing trade magnitude. | Does not include win frequency by itself. |
For your 2026 reporting, name the measure before interpreting it. A payoff ratio calculated in money also reflects differences in position sizing. A risk-normalised series answers a different question.
A favourable payoff ratio does not establish profitability. Loss frequency still matters. So do costs and the completeness of the trade sample.
05
Review the difference without rewriting the plan
Save the original plan separately from later edits. Otherwise the journal becomes a description of what happened rather than a record of what you intended. A moved target should not silently replace the first target.
- Preserve the plan. Keep the original entry, stop, target and monetary risk.
- Reconcile execution. Match fills and position changes to the trade record.
- Check accounting. Reconcile charges, adjustments and account-currency amounts.
- Classify differences. Separate planned management from unplanned decisions and execution effects.
- Review patterns. Compare repeated situations rather than drawing a rule from an isolated outcome.
Use the same categories throughout your 2026 journal. Changing labels halfway through makes similar decisions appear unrelated. Preserve the underlying records when you revise a category.
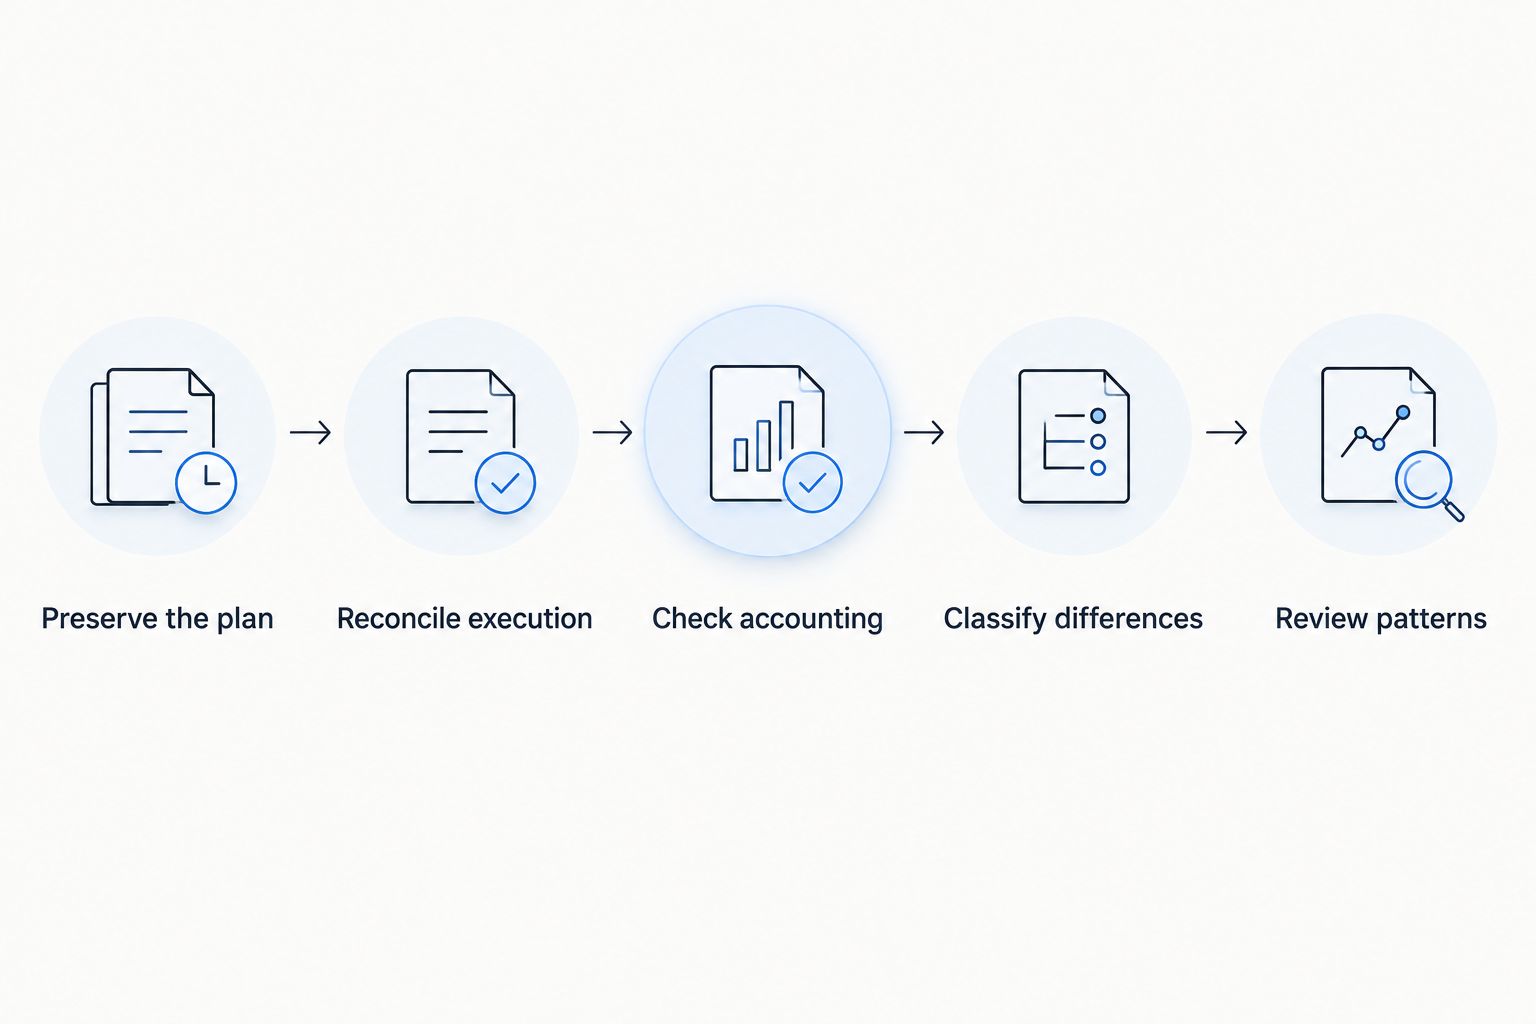
Preserve the original plan before classifying why the realised result changed.
If the initial stop or original size is missing, do not reconstruct it from the final outcome. Mark the risk baseline as unavailable. Keep the recorded account result without presenting an unsupported R-multiple.
Should I change the denominator after moving my stop?
Keep original risk fixed when measuring performance against the original plan. Track the revised stop separately. Otherwise a smaller denominator can make the same monetary result appear stronger without any additional profit.
Does an early exit mean I traded badly?
An early exit alone does not establish decision quality. Compare the exit with your recorded management rules and the information available at the time. A profitable deviation is still a deviation.
Conclusion
Your realised result needs an explanation, not a revised memory of the plan. In your 2026 review, preserve the target and original risk. Then reconcile every fill and relevant account entry.
The useful question is not simply whether the ratio was lower. Ask whether the difference came from execution, accounting or a changed decision. Each explanation points to a different review task.
Keep original risk fixed. Explain the difference between the target and the result.
FAQ
What is a realized risk reward ratio?
A realized risk reward ratio describes achieved reward relative to a stated risk measure. For an individual trade, net result divided by original monetary risk is more precisely called a realised R-multiple.
Why is my realised return lower than my target?
Your realised return is lower when actual exits, position changes or costs reduce the result relative to the planned target. Check fills and account entries before attributing the difference to trading behaviour.
How do partial closes affect realised risk-reward?
Partial closes make the total result depend on every closed portion and its execution price. The final exit alone cannot represent the whole trade.
Should I include commission and financing in my trade review?
Include applicable commission and financing when calculating a net trade result. Check whether the reported result already includes those entries before subtracting them.
Does moving my stop change my original R-multiple?
Moving your stop does not change the original risk baseline used for a consistent R-multiple. Record the revised stop separately rather than replacing the original denominator.
Is a high realised payoff ratio enough to show profitability?
A high realised payoff ratio is not enough to show profitability. Win frequency and the accounting basis of the results also matter.
Can I calculate an R-multiple without recording initial risk?
You cannot calculate a supported R-multiple without a reliable initial risk baseline. Keep the closed monetary result and mark the missing baseline rather than guessing.
One last thing
A stop moved to the entry price does not erase the risk you originally accepted. It also does not guarantee a cost-free exit. Preserve the original denominator even when the current stop makes the trade feel different.
Related guides
This article is for educational purposes only and does not constitute investment advice. Trading CFDs and other leveraged products carries a high level of risk and may not be suitable for all investors.


