Commodity education · 2026
Contango can create a return drag for long commodity exposure that rolls into later futures contracts. Backwardation can provide a return contribution. Neither guarantees a profit or loss. Your result also depends on price movements, the contracts held and the instrument’s adjustment rules.
TL;DR
- Contango vs backwardation describes futures curve shape, not a guaranteed direction for commodity prices.
- Long futures exposure generally faces negative roll yield in contango and positive roll yield in backwardation, other things equal.
- A rollover adjustment is not automatically an additional loss. Check what it offsets.
- VCG Markets offers commodity exposure through its multi-asset brokerage. Check instrument terms before applying futures-curve analysis.
Start by separating the commodity’s cash price from its dated futures prices. The same distinction appears in cash index and futures prices: related markets do not necessarily display the same quote.
01Read the curve
02Understand the roll
03Check the instrument
01
How do contango and backwardation affect commodity exposure?
Contango and backwardation affect the relationship between delivery dates. They matter when your exposure follows futures contracts rather than the commodity’s immediate cash price. The curve describes a price relationship today. It does not promise tomorrow’s price.
| Feature | Contango | Backwardation |
| Curve shape | Later contracts trade above nearer contracts. | Later contracts trade below nearer contracts. |
| Long rolling exposure | Generally negative roll yield, other things equal. | Generally positive roll yield, other things equal. |
| What it cannot establish | Whether the long position will lose overall. | Whether the long position will profit overall. |
A curve does not have to slope consistently across every expiry. Nearby contracts can show backwardation while more distant contracts show contango. Compare the dates your instrument actually uses. A headline about the overall commodity market is not enough.
02
Why this matters
Getting the commodity’s direction right does not establish your instrument’s return. A position linked to futures reflects the contracts it follows. Those contracts can behave differently from spot prices.
This distinction matters when reviewing performance in 2026. Compare like with like. A spot chart, a dated futures chart and a continuously adjusted chart answer different questions.
A commodity can rise while a rolling long exposure trails that rise. Conversely, favourable curve effects can support a return without preventing a loss. Separate the market move from the exposure structure.
Your holding period also matters. Crossing a contract transition introduces a different accounting question from closing beforehand. Even without a roll, changes in the curve can move the particular futures contract you hold.
03
Why the futures curve varies
A futures curve reflects conditions across delivery dates. Carrying costs and the value of immediate access both matter. Their balance differs between commodities and changes over time.
- Storage: Holding physical inventory involves storage costs. Those costs influence the economics of buying now and selling for later delivery.
- Financing: Capital tied up in inventory has a financing cost. Interest rates therefore influence the cost of carrying a commodity.
- Immediate availability: Access to physical stock can have operational value. This is often called convenience yield.
- Seasonality: Production cycles and seasonal consumption affect particular delivery months. Adjacent contracts need not face identical conditions.
- Supply disruption: An immediate shortage can affect nearby delivery more sharply than later delivery. The curve can change without moving uniformly.
These are drivers, not trading instructions. Read them alongside the contracts themselves. The guide to oil supply and demand reactions covers the physical-market side of that assessment.
04
How rolling changes commodity exposure
Rolling replaces exposure to an expiring contract with exposure to a later contract. For a long futures position, this normally means closing the nearer contract and opening the later one. The dates change. The economic exposure continues.
- Identify contracts: Establish which expiry supplies the current exposure and which expiry replaces it.
- Compare dates: Examine the price relationship between those contracts. Do not substitute an unrelated spot quote.
- Read adjustments: Check how the instrument treats any difference between the outgoing and incoming reference prices.
- Reconcile results: Separate trading profit or loss from cash adjustments, funding and execution charges.
Use this sequence when checking a rollover in 2026. The contract spread is not automatically an immediate loss equal to that spread. Futures exposure is not the same as paying the full quoted price for a physical purchase.
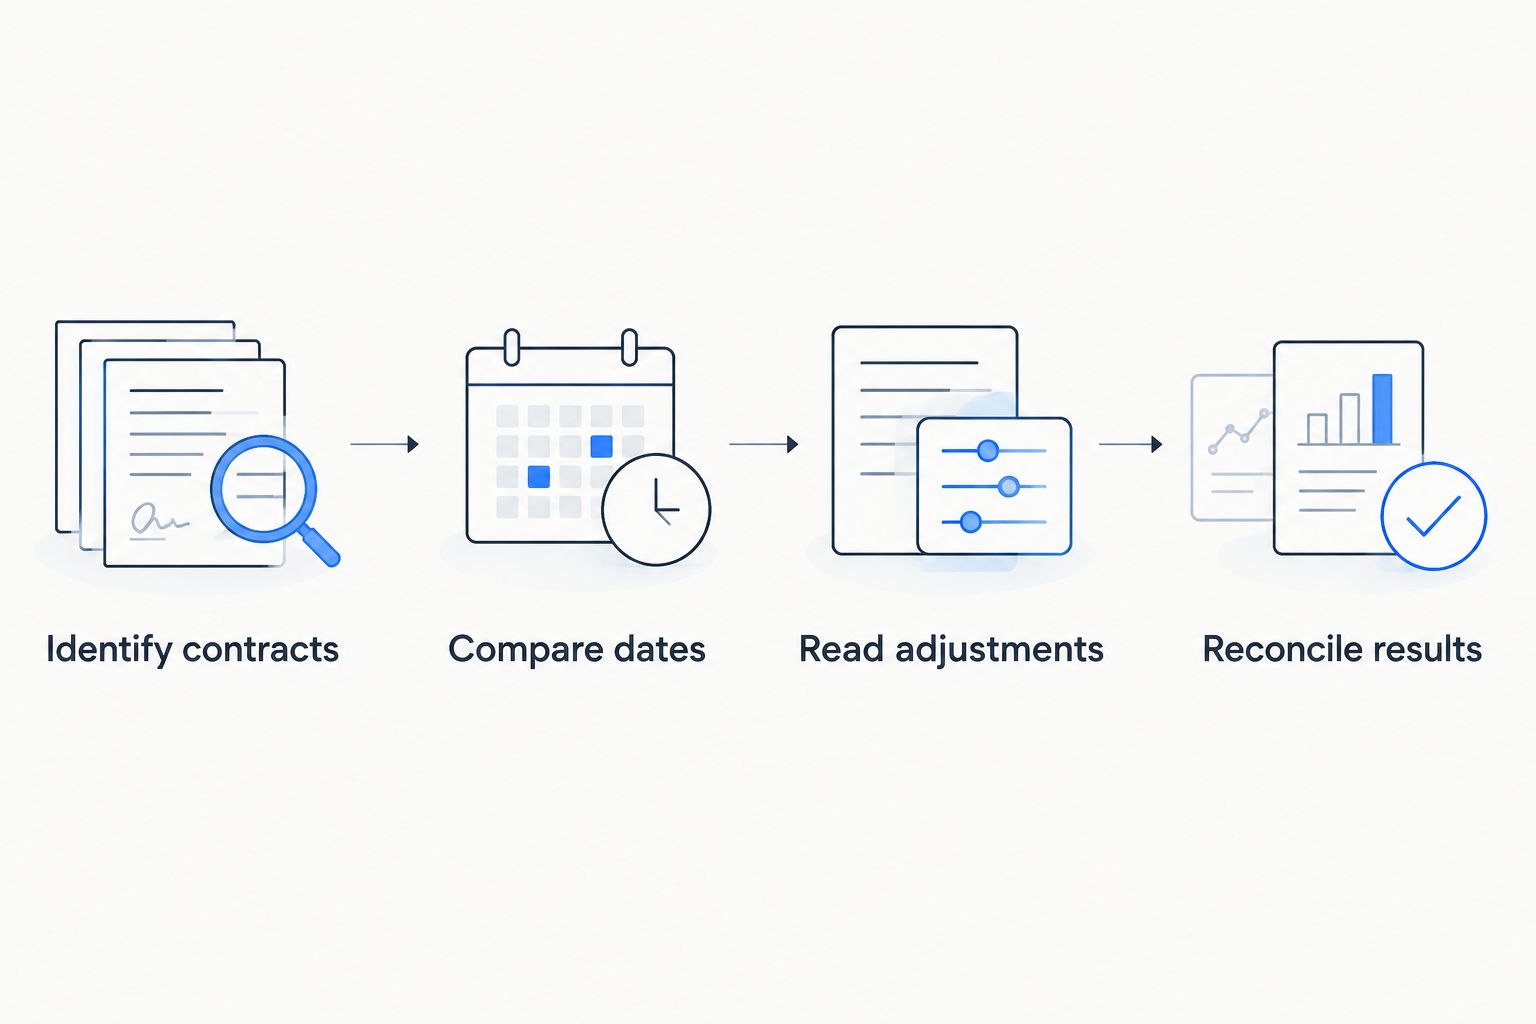
Separate the change in reference contract from the account entries that accompany it.
Roll yield concerns how rolling exposure performs as futures prices evolve and converge towards spot near expiry. The curve observed at rollover helps explain that effect. It does not fix the subsequent price path.
05
Contango: a potential drag on rolling long exposure
In contango, later futures trade above nearer futures. A rolling long position moves into the higher-priced contract. If spot remains unchanged and the futures premium erodes towards expiry, that convergence works against the long position.
The qualification matters. Spot can rise enough to outweigh the drag. The curve can also flatten or reverse. Contango alone does not establish a losing trade.
The useful information is the premium attached to later delivery. The limitation is treating that premium as a forecast. Contango identifies a structural consideration. It is not a standalone sell signal.
For short exposure, the direction of the convergence effect reverses under the same assumptions. That does not remove the risk of a rising futures price. Directional losses can outweigh favourable curve effects.
06
Backwardation: a potential contribution to rolling long exposure
In backwardation, later futures trade below nearer futures. A rolling long position moves into the lower-priced contract. If spot remains unchanged and the discount narrows towards expiry, convergence supports the long position.
The benefit is conditional. Falling spot prices can outweigh it. A change in the curve can alter it before the contract expires.
Does backwardation mean commodity prices will rise?
Backwardation does not guarantee rising commodity prices. It describes the current relationship between delivery dates. Immediate demand for physical supply can support nearby prices without establishing the next market move.
Can you lose money in backwardation?
You can lose money in backwardation. A favourable roll contribution does not protect a long position against a larger fall in its futures price. It also does not cancel funding or execution charges.
07
What should you check before holding commodity exposure in 2026?
Start with the instrument specification. A commodity name does not tell you how the quote is constructed. Establish the reference price before interpreting the curve.
- Reference market: Identify whether the instrument follows a dated future or another pricing method.
- Transition rules: Find the contract-change schedule and the treatment of open positions.
- Account entries: Distinguish a reference-price adjustment from financing or an execution charge.
- Chart construction: Establish whether historical prices are adjusted across contract changes.
- Position direction: Analyse long and short exposure separately. Their sensitivity to convergence differs.
A continuous chart can help show history. An adjusted history is not necessarily the sequence of executable prices your account experienced. Reconcile the chart with the contract record and account statement.
Is a rollover adjustment the same as a fee?
A rollover adjustment is not necessarily a fee. It can offset a change in the reference quote. Read both entries together before identifying an additional cost.
FAQ
What is the difference between contango and backwardation?
Contango means later futures trade above nearer futures. Backwardation means later futures trade below nearer futures. The relationship can differ across parts of the same curve.
Is contango bad for long commodity exposure?
Contango generally creates negative roll yield for rolling long futures exposure, other things equal. Rising commodity prices can outweigh that effect, so contango does not guarantee a loss.
Is backwardation a reason to buy a commodity?
Backwardation alone is not a sufficient reason to buy a commodity. It can support rolling long exposure through convergence, but adverse price movements can outweigh that contribution.
Do commodity ETFs always track the spot price?
Commodity ETFs do not all track spot prices in the same way. Check the fund documents to establish whether exposure comes from physical holdings, futures or another structure.
Does every commodity position have a rollover?
Not every commodity position involves rolling futures exposure. The answer depends on the instrument and whether you hold it across a contract transition.
Can I calculate my return from the futures curve alone?
The futures curve alone cannot establish your return. You also need the price path, position direction, contract selection and applicable account charges or adjustments.
Conclusion
For commodity exposure in 2026, read the curve and the instrument terms together. Contango and backwardation explain a relationship between delivery dates. Neither is a complete return forecast.
One final check: compare a rollover adjustment with the simultaneous change in the quoted reference price. Looking at either entry alone can misstate its economic effect. That reconciliation matters more than the label attached to the entry.
Read the curve. Check the contract. Reconcile the result.
This article is for educational purposes only and does not constitute investment advice. Trading CFDs and other leveraged products carries a high level of risk and may not be suitable for all investors.